VW sells its cars at roughly twice BYD’s price level. Yet both keep the same 4.3 cents of operating profit per euro of revenue.
This week BYD announced 1.02 million employees, more than Toyota, GM, Ford and Tesla combined. The internet did the obvious math: BYD makes about 5 cars per employee, VW about 12. Case closed: BYD is inefficient.
I ran the H1 2026 numbers like-for-like instead. Underlying, before one-offs:
| Metric | VW Group | BYD |
|---|---|---|
| Revenue per car | ~€37k | ~€19k |
| Operating profit per car | ~€1.6k | ~€1.0k |
| Operating margin | 4.3% | 4.3% |
| Net margin | 2.0% | 3.6% |
| Cars per employee (annualised) | ~12 | ~4 to 5 |
Notes: VW operating margin before special items. VW revenue per car includes trucks and financial services, so it is overstated. Euro at ~8.2 CNY. Per-car figures and margins are the author’s calculations.
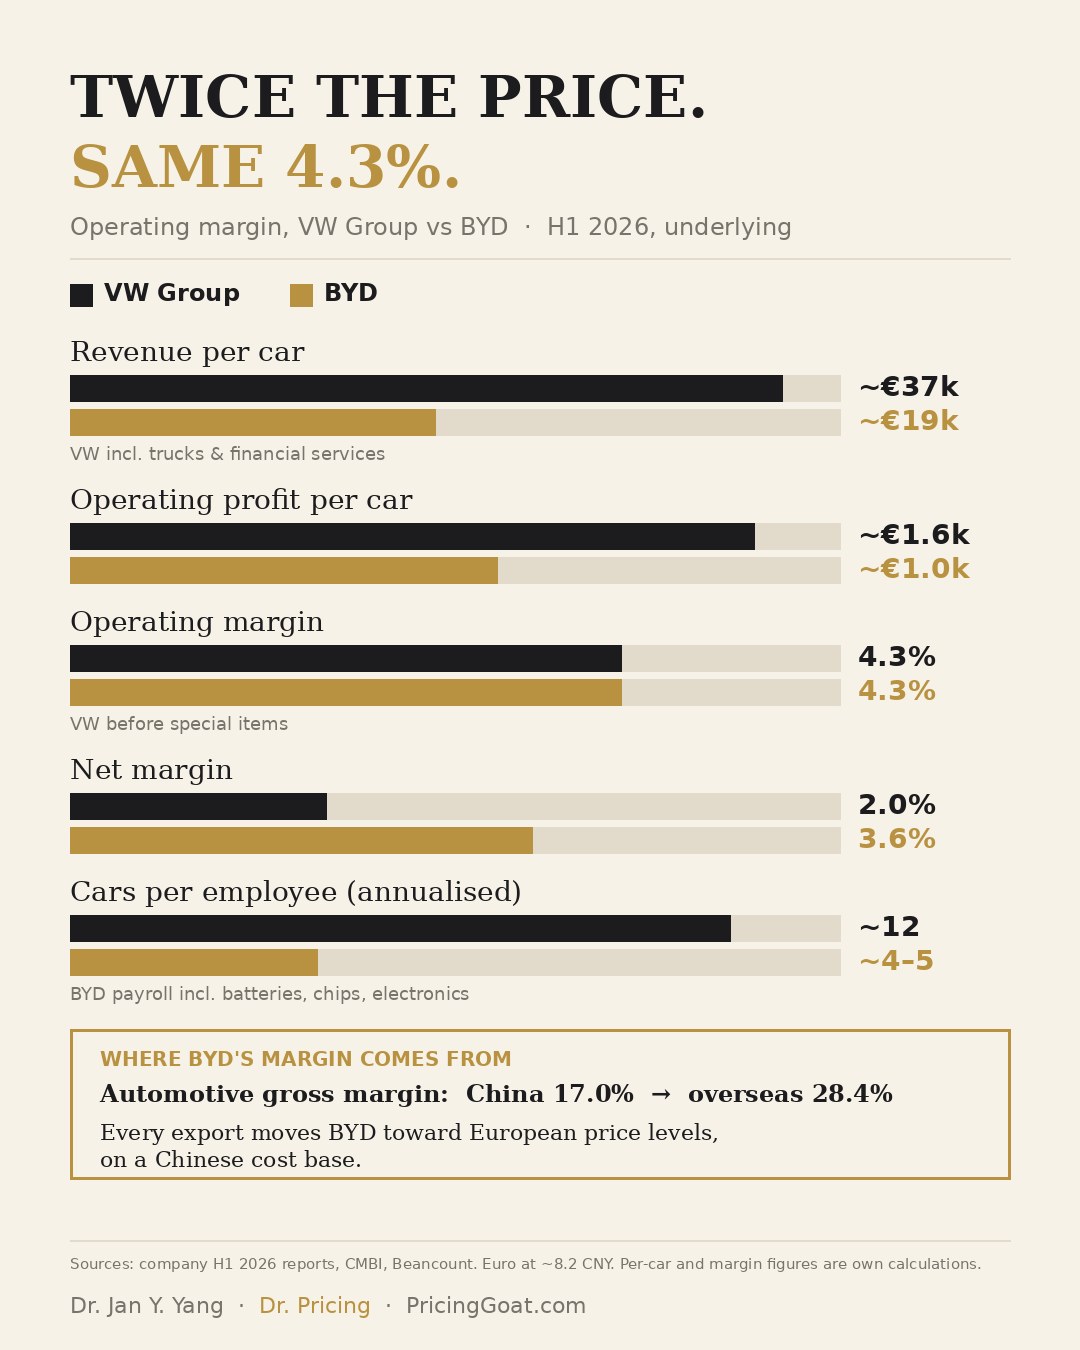
In absolute terms VW still earns more per car. But it needs twice the revenue to get there: twice the money flows through the system, and only about 1.6 times the profit stays.
Half the price, the same share
So how does a car at half the price keep the same share as operating profit?
1. BYD keeps the supplier margin. It makes its own batteries, chips and motors. VW buys them, so a share of every euro it charges flows straight to the supply chain. That’s also why BYD’s headcount looks so big: it carries jobs that sit on other companies’ payrolls in Germany.
2. VW’s higher price level is matched by a higher cost level. European wages, energy and legacy capacity absorb what the higher price brings in.
3. VW’s foreign-brand bonus in China is gone. For decades, being a German brand in China was worth something at the till. Deliveries there fell 26% in H1.
The part that should worry Wolfsburg
BYD’s automotive gross margin is 17.0% in China and 28.4% overseas. Every car it exports moves it toward European price levels, while it keeps a Chinese cost base. VW, meanwhile, guides to an operating margin of up to 1% for 2026.
The lesson for every pricing team
A higher price level is not pricing power. What counts is how much of the price your cost structure lets you keep.
not by default.
In your industry, what decides margin: the price you charge, or the share of it you keep?
First published on LinkedIn, October 2026. Also available in Chinese: 售价高出一倍,利润率却一样:大众和比亚迪的账,到底该怎么算?
Sources